Marvell Technology agreed Monday to acquire optical-networking specialist Lumentum in an all-stock transaction carrying an implied enterprise value of $115 billion. The deal would join Marvell’s custom chips, switches and electrical-to-optical signal processors with Lumentum’s lasers, transceivers and optical switching hardware, creating a much broader supplier for AI data-center connectivity.
Under the agreement announced November 2, each Lumentum common share will convert into 4.5 Marvell shares. That fixed exchange ratio valued Lumentum at about $1,132 per share using the companies’ unaffected October 28 closing prices, a 23.9% premium. The boards approved the transaction unanimously, but shareholders at both companies and regulators still have to sign off. Marvell and Lumentum are targeting a close in the first half of 2028.
The long timetable matters. This is an agreement, not a completed acquisition, and the dollar value attached to each Lumentum share will move with Marvell’s share price before closing. Axios described it as the largest merger between public technology companies, while the companies put the combined enterprise value above $275 billion.
What Marvell is buying
AI accelerators receive most of the attention in data-center spending, but the processors are only useful when they can exchange data quickly enough. As clusters expand from a few accelerators to thousands of XPUs spread across racks and buildings, moving bits becomes a system-level constraint. Copper remains useful over short distances, but signal loss, power and bandwidth density increasingly push longer and denser links toward light.
Marvell already sells several pieces of that path: high-speed SerDes interfaces, optical digital signal processors, data-center switches, custom compute silicon, silicon photonics and interconnect products. Lumentum supplies many of the components that generate, route and receive the light, including high-power lasers, optical transceivers, photonic components and optical circuit switches.
The proposed combination therefore reaches beyond a conventional chip acquisition. Marvell wants to co-design the electrical interface, photonic integrated circuit, laser and switching layer as one system, then offer customers pre-validated optical engines instead of making cloud operators assemble and qualify each component separately.
The two companies have already demonstrated that engineering relationship. At the 2025 Optical Fiber Communication Conference, they showed a 450-gigabit-per-lane optical interface pairing Marvell’s 400G-per-lane PAM4 technology with a Lumentum indium-phosphide transmitter. That work was aimed at future 3.2-terabit transceivers, the kind of component large AI fabrics will need as accelerator links become wider and faster.
Why the deal reaches from chips to lasers
The companies divide the AI connectivity problem into several distances. Scale-up links connect accelerators inside a tightly coupled system. Scale-out networking joins racks into a larger cluster. Scale-across links connect data centers or campuses. Emerging scale-in designs move optical I/O still closer to the compute package.
Each step creates different requirements for latency, reach, power, packaging and reliability. A pluggable transceiver at the edge of a switch is relatively easy to replace. Co-packaged optics or an optical I/O engine beside an accelerator offers higher density, but it also ties the laser, photonics and electrical design more closely to the chip and package. A failure or late component can hold up an entire platform.
Marvell’s merger presentation argues that controlling more of this stack will shorten qualification cycles and reduce integration risk. It also places the addressable market for the combined portfolio at $550 billion. That figure is a company estimate rather than a forecast of sales, but it shows the ambition: Marvell is positioning itself as a full-stack connectivity supplier, not merely a merchant silicon vendor.
The ownership and savings math
Current Marvell shareholders would own about 67% of the combined company on a fully diluted basis, with Lumentum holders owning about 33%. Marvell chairman and CEO Matt Murphy would retain both roles. Three Lumentum directors, including CEO Michael Hurlston, would join Marvell’s seven-member board.
The companies project more than $1 billion in annual run-rate synergies, primarily from cost of goods sold, and expect the transaction to increase Marvell’s non-GAAP earnings per share during the first year after closing. Those are management targets, not guaranteed savings. Investors will need the forthcoming Form S-4 and proxy materials to see the integration assumptions, one-time costs and sensitivity behind them.
The all-stock structure avoids a large cash payment, but it transfers valuation risk to both shareholder groups. Because the exchange ratio is fixed, a fall in Marvell’s stock reduces the market value Lumentum holders would receive; a rise increases it. The headline $1,132 figure is a reference-point calculation, not a cash floor.
Closing risk stretches into 2028
Marvell’s November 2 regulatory filing lists several conditions: approval of the share issuance and charter amendment by Marvell investors, adoption of the merger agreement by Lumentum investors, U.S. antitrust clearance, other regulatory approvals, an effective Form S-4 and authorization to list the new shares on Nasdaq.
The initial outside date is November 1, 2027. If specified regulatory conditions remain unresolved, it can extend in stages to February, May and August 2028. That schedule gives authorities time to examine a supplier that would span custom silicon, switching, optical DSPs, silicon photonics, lasers and transceivers across several layers of AI infrastructure.
Customers will have their own questions. A vertically broader Marvell may simplify system design, but cloud operators and equipment vendors also rely on competing suppliers to preserve pricing leverage and avoid single-source risk. The most important evidence will be design wins that use multiple parts of the combined stack without forcing customers into an all-Marvell architecture.
What to watch next
The next decisive document is the joint proxy and Form S-4, which should contain fuller financial projections, board deliberations, fairness analyses, regulatory risks and integration costs. Technical progress is equally important. Watch for customer qualification of co-packaged optics, external laser sources, optical I/O engines and optical circuit switching rather than broad claims about AI demand.
Until the transaction closes, Marvell and Lumentum remain separate companies. The deal’s strategic case is straightforward: ever-larger AI systems need more bandwidth at lower energy per bit, and the boundary between the chip and optical link is moving inward. Whether the merger delivers on that case will depend on regulatory clearance, customer support and the hard manufacturing work of making advanced photonics reliable at volume.
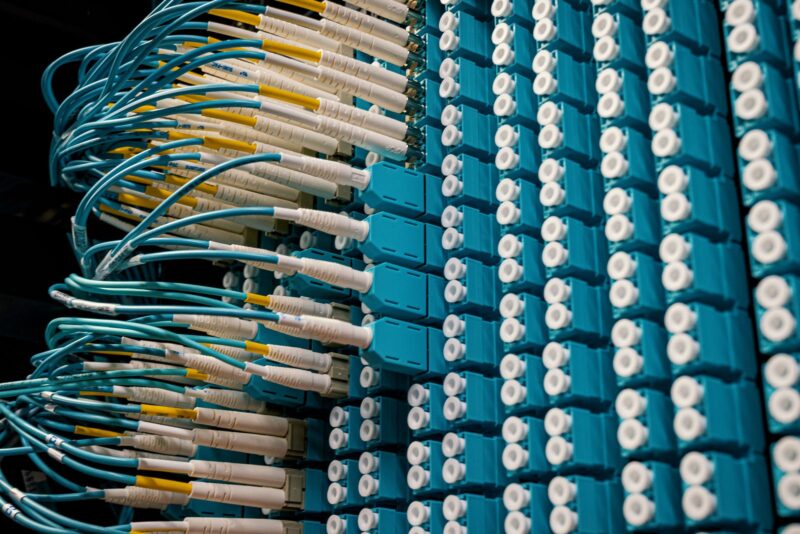
Featured image: Fiber-optic networking equipment. Photo by Brett Sayles via Pexels.