Apple reported a record $114.5 billion in fiscal fourth-quarter revenue on November 2, giving John Ternus a strong first earnings report as CEO. The more consequential part of the update was the outlook: Apple expects its gross margin to fall to between 45% and 46% in the holiday quarter as memory prices rise and server-side Siri AI begins adding a recurring inference bill.
The quarter ended September 26, before the iPhone Duo shipped on October 23, and included only nine days of iPhone 18 Pro sales. It nevertheless produced record September-quarter iPhone revenue, an all-time high for Services and $30.7 billion in net income. Apple earned $2.10 per diluted share, although tariff refunds contributed $0.05 of that figure and roughly one percentage point to the company’s 47.9% gross margin, according to Apple’s results announcement.
The results beat the $113.4 billion revenue and $1.99 per-share profit analysts expected in a FactSet survey cited by The Associated Press. They also set up a harder comparison for the current quarter, when Apple must absorb a full launch cycle, supply constraints and AI cloud costs at the same time.
iPhone and Mac drove the quarter
Apple’s consolidated financial statements show that iPhone and Mac supplied most of the growth. Services remained Apple’s second-largest business, but its 9.8% year-over-year growth trailed the hardware categories that did well.
| Business | Q4 FY2026 revenue | Year-over-year change |
|---|---|---|
| iPhone | $57.6 billion | Up 17.5% |
| Mac | $10.8 billion | Up 23.7% |
| iPad | $6.2 billion | Down 10.4% |
| Wearables, Home and Accessories | $8.3 billion | Down 7.9% |
| Services | $31.6 billion | Up 9.8% |
Greater China revenue rose 21% to $17.5 billion, while total product sales increased to $82.9 billion. Apple’s reported numbers imply a product gross margin of about 37.2% and a Services gross margin of about 76%. That gap explains why the cost of running Siri in the cloud matters even though Apple still makes most of its revenue from devices: cloud inference lands inside the company’s unusually profitable Services business.
Research and development spending also jumped 32% from a year earlier to $11.7 billion for the quarter. Apple did not break out how much went to AI, silicon or individual products, so the filing does not support assigning that increase to Siri alone.
Memory and Siri AI will pressure holiday margins
Apple expects holiday-quarter revenue to grow between 7% and 10%, which would make it the company’s largest quarter by revenue. But the projected 45% to 46% gross margin is 1.9 to 2.9 percentage points below the just-reported figure. Part of that difference is mechanical because the September quarter included the tariff-refund benefit. The rest reflects higher input and operating costs.
Ternus described current memory pricing as “unprecedented” during the earnings call. Apple has already raised prices on Macs and iPads in June and on iPhones in September, and it has some lower-cost inventory left to soften the impact. The company nevertheless expects memory purchase prices to keep increasing after December while that inventory buffer shrinks, according to Reuters’ report on the results.
Siri AI introduces a different kind of cost. Requests handled on an iPhone, iPad or Mac do not create a per-query cloud bill for Apple. Requests routed to Private Cloud Compute consume server capacity and are recorded in Services cost of sales. CFO Kevan Parekh said the balance between on-device and cloud processing is still too new to forecast reliably. Reuters reported that Siri AI is already handling 2.5 billion requests a day, making even a modest cloud share material at Apple’s scale.
Apple has also said it plans to place usage limits on server-side Siri AI and photo-editing features, with expanded access available through iCloud+ plans. The company has not disclosed the included allowances or the price of extra capacity. That leaves an important question unanswered: whether Apple can turn the inference cost into subscription revenue without making core Siri features feel metered.
The iPhone Duo opportunity is mostly in the next quarter
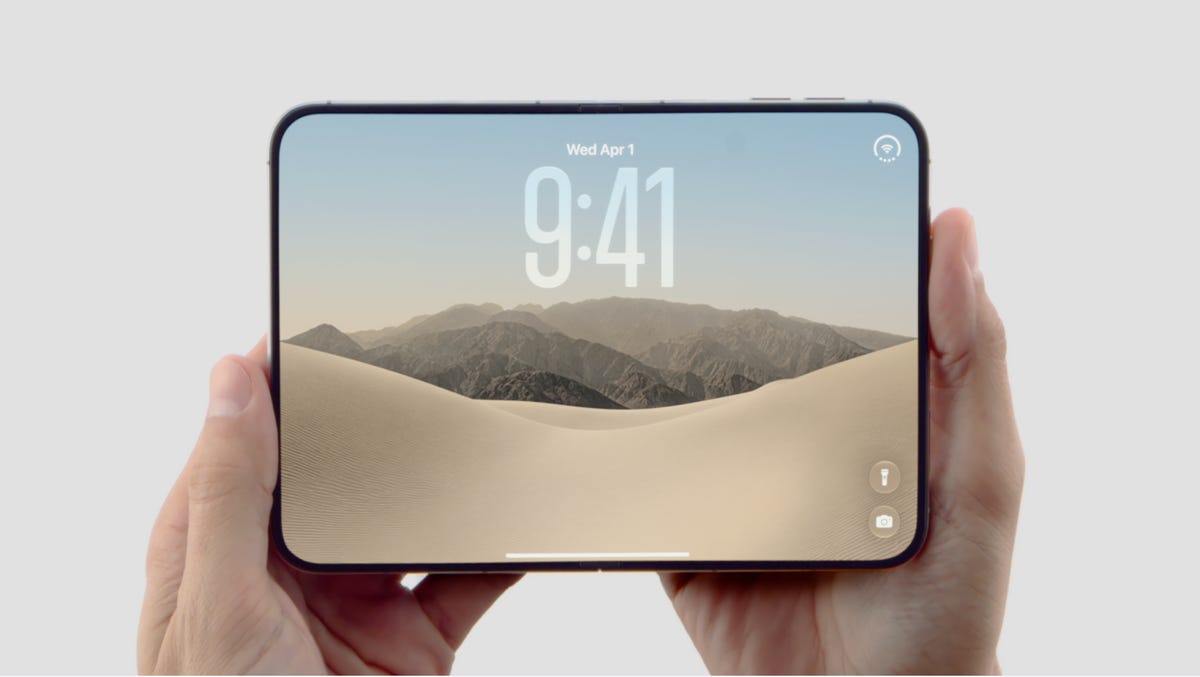
The iPhone Duo’s October 23 release means none of its sales appear in the $114.5 billion quarter. Ternus told Reuters that demand is running ahead of supply and Apple cannot yet say when the two will balance. That gives the company a visible source of holiday growth, but a sold-out device contributes only as fast as Apple can build and ship it.
Supply pressure is not limited to the foldable iPhone. Apple said iPhone, iPad and Mac availability was constrained in the September quarter by demand and limited capacity for the advanced process nodes used to manufacture their systems-on-chip. COO Sabih Khan indicated that advanced-node pressure should ease as more of the lineup moves to 2-nanometer chips, while Mac and iPad could remain constrained by memory during the December quarter.
The timing matters when reading the guidance. Apple is forecasting its best revenue quarter while launching the Duo, touchscreen MacBook Pro, HomeView and new home hardware. It is simultaneously warning that the profit retained from each dollar of sales will decline.
What buyers and investors should watch next
- Product prices: Apple has already used higher Mac, iPad and iPhone prices to offset memory inflation. It did not announce another increase on the call, but continuing component pressure makes pricing and storage-tier changes worth watching.
- iPhone Duo availability: Demand is not the same as shipped revenue. Delivery times and regional stock will show whether Apple can convert launch interest during the holiday window.
- Siri AI limits: The eventual iCloud+ allowances will reveal how Apple divides a flagship assistant between an included device feature and a paid cloud service.
- Services profitability: Services revenue is still growing, but server-side inference adds a new variable to a business whose high margin has supported Apple’s overall profitability.
Apple enters the holiday quarter with strong device demand and a broader product lineup than it had a year ago. Its first earnings call under Ternus also made the trade-off unusually clear: the company’s newest hardware and AI services can expand revenue, while the memory and compute behind them make that growth more expensive.